




- 40+ yearsprofessional experience
- 30+ yearsleading credit risk management
- ≈3,000dealers and customers in the ecosystem
- Billion€peak trade receivables portfolio
IPROFILE
Four decades in credit risk management
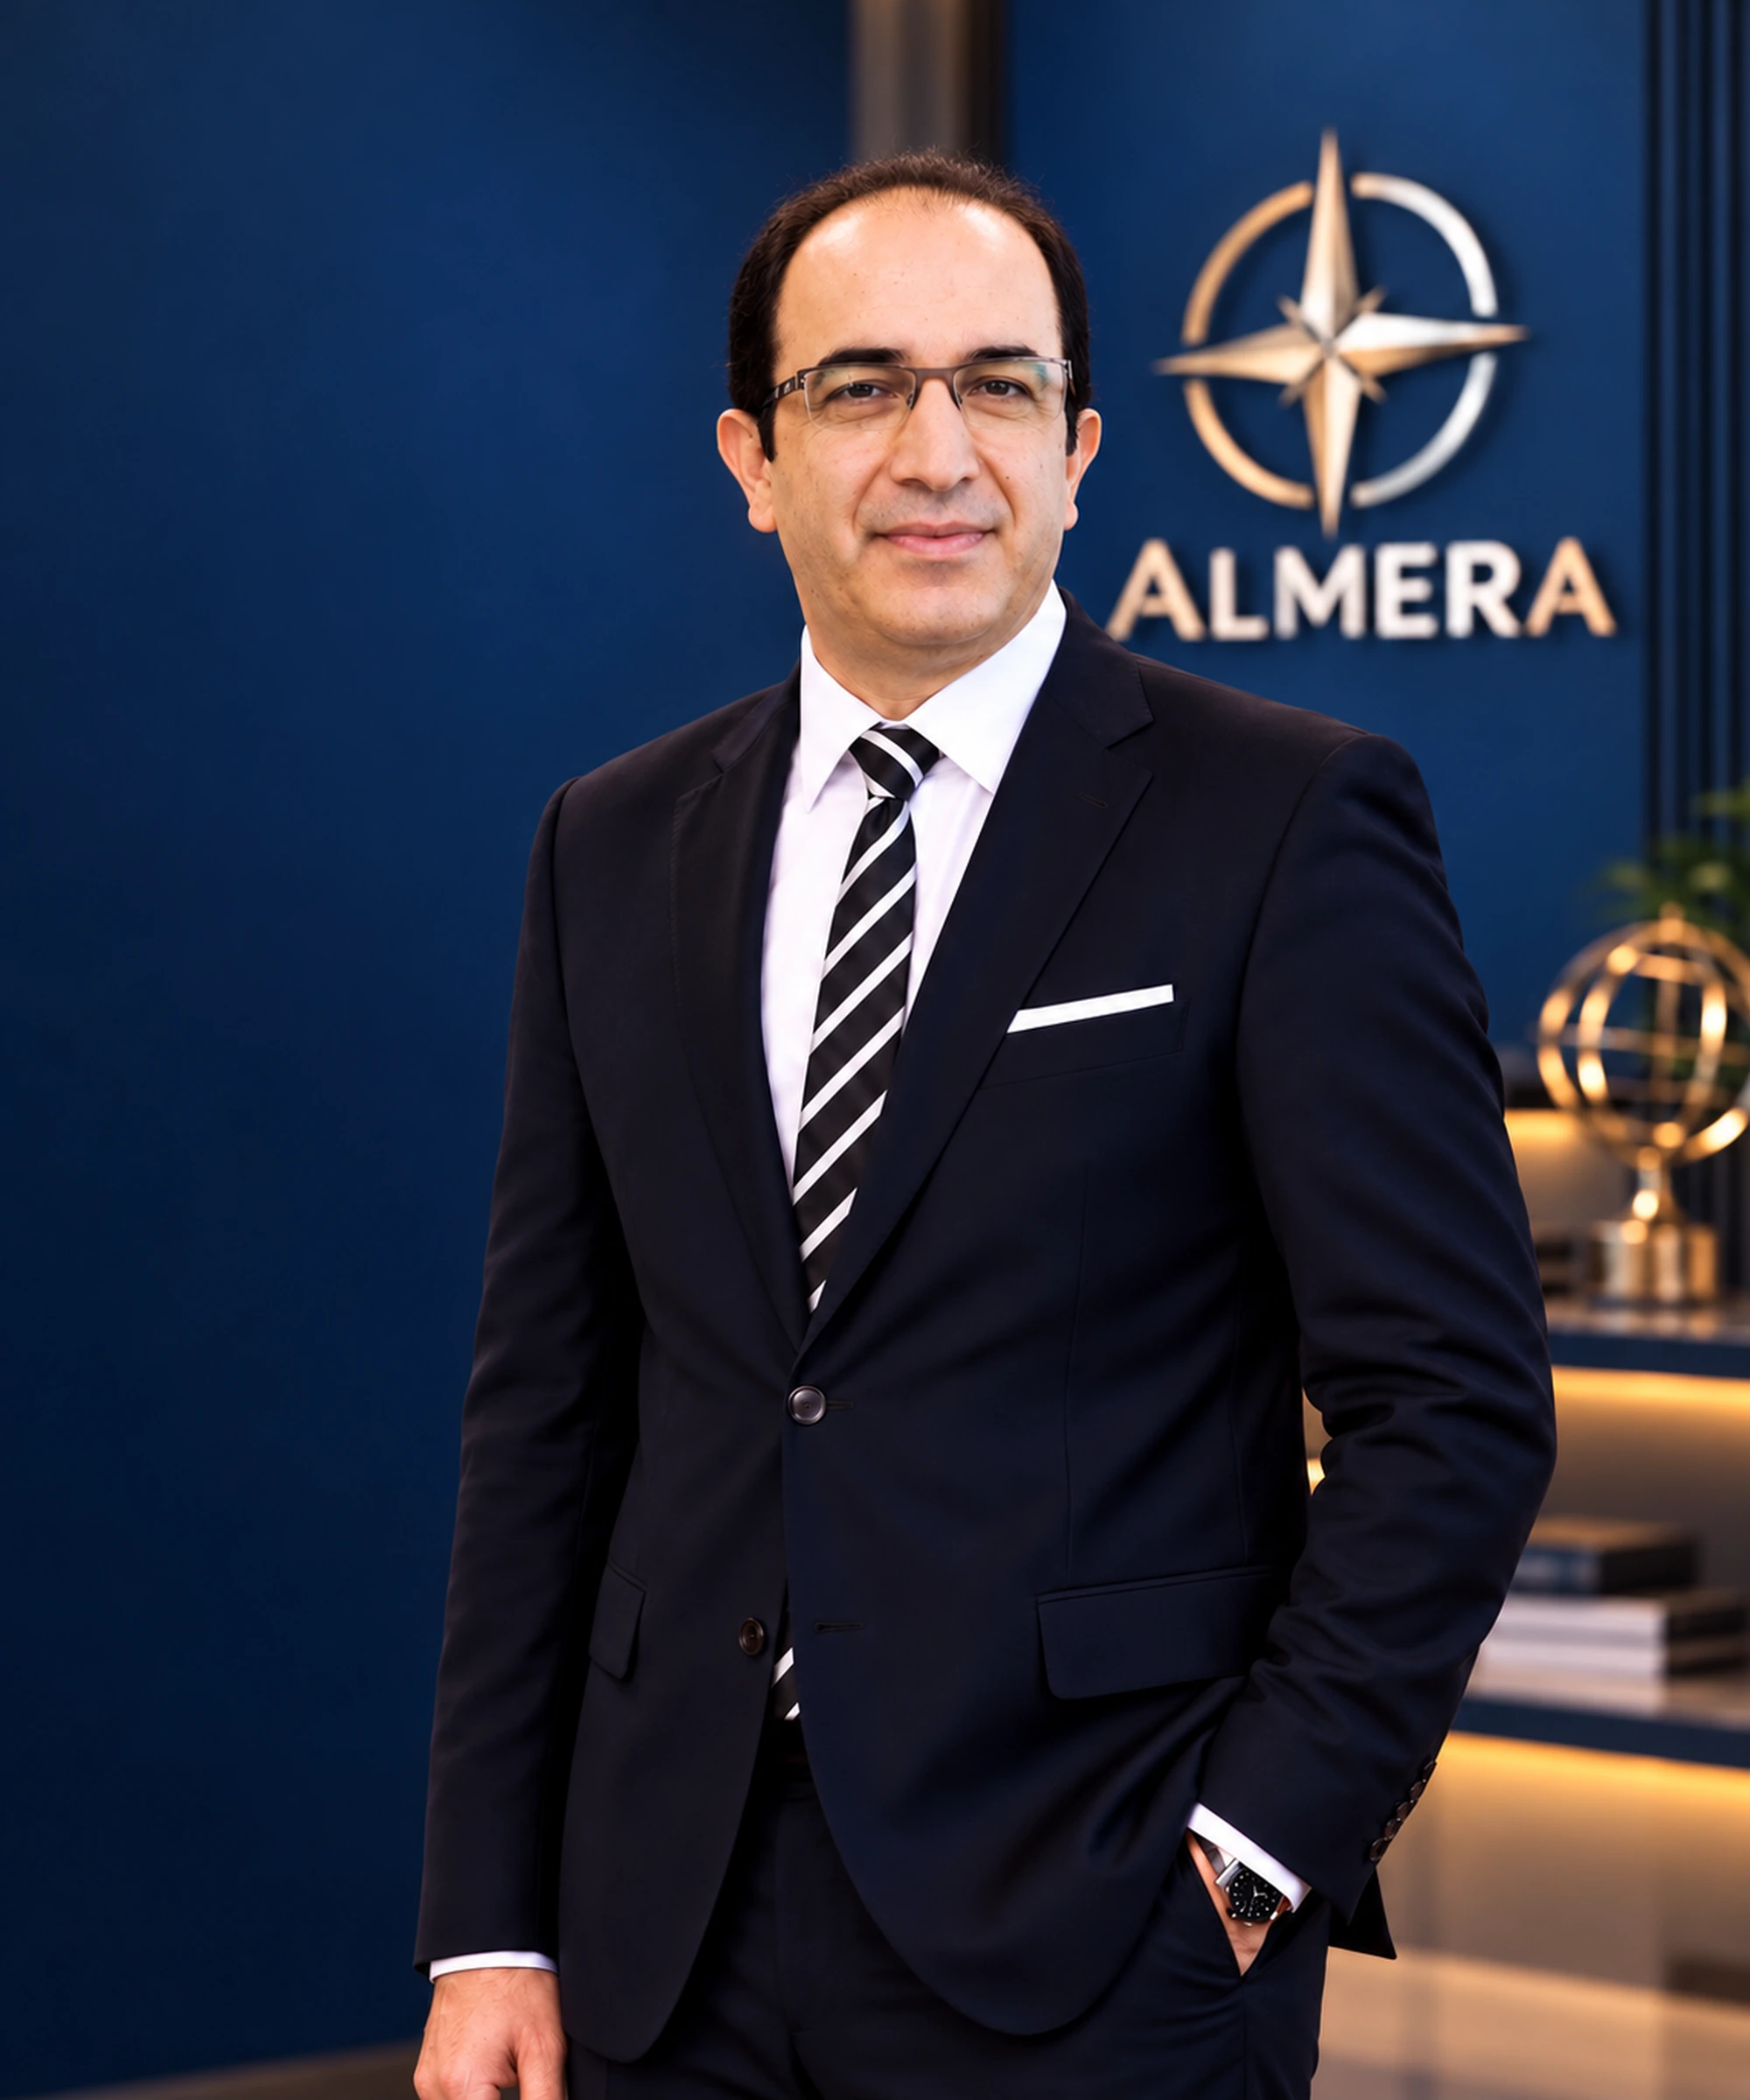
Mehmet Nuri Alptekin is a senior executive and system builder with more than 40 years of professional experience in credit risk management, trade receivables management, financial analysis, credit limits, collateral and collection systems.
Over his career he has led the credit risk and trade receivables management systems of a broad commercial ecosystem of around 3,000 dealers and customers , and has carried senior decision-making and initiative responsibility for a trade receivables portfolio that at times reached billions of euros.
At the heart of his career has been not merely managing existing risks, but building systems that open the way for sales by taking healthy, manageable risks while protecting the company’s capital and cash flow.
- Türkiye
- Middle East
- North Africa
- Turkic Republics
IIMANAGEMENT APPROACH
Leadership. Initiative. System.
Three concepts stand out in Mehmet Nuri Alptekin’s approach to management:
- 01LeadershipTaking responsibility for a decision and its outcome.
- 02InitiativeBeing able to take calculated, manageable risk amid uncertainty.
- 03SystemEnsuring the right decisions can be reproduced without depending on individuals.
In this approach, credit risk management is not a brake that protects the company but leaves it unable to move. Well-designed credit risk management is the management infrastructure that enables the company to grow in a controlled, sustainable way.
IIIEXPERIENCE
Leadership That Builds Systems
“40 years of experience becomes leadership only when you stay as current as you were 40 days ago.”
01Career and Scale
He began his career in banking, in credit, credit intelligence and financial analysis, and spent 39 years of his professional life in real-economy credit risk management within a corporate group operating nationally and internationally. For more than 30 of those years he led credit risk management at manager and director level.
He gained customer and dealer credit risk experience in markets spanning Türkiye, the Middle East, North Africa and the Turkic Republics, and led the creation and management of credit policies, limit and collateral systems, and risk-monitoring and collection processes across diverse economic conditions, commercial structures and customer profiles.
This leadership was not limited to controlling and collecting existing receivables; through the credit decisions taken and the risks managed, it also covered building and running the credit risk infrastructure that allowed billions of euros of commercial activity to be sustained through credit sales.
Experience at this scale shaped the conviction that the core question of credit risk management is not avoiding risk, but correctly determining which risk can be taken under which conditions .
02The Sales–Risk Balance and Initiative
Balance and initiative sit at the centre of Alptekin’s approach to credit risk management. Overly protective credit policies can block sales; uncontrolled growth can threaten the company’s capital, cash flow and profitability. The task of credit risk management, therefore, is not simply to limit risk or say “no” to sales.
The real task is to open the way for healthy sales by selling to the right customer, at the right limit, on the right terms, with a suitable collateral structure, taking only as much risk as the company can carry.
In this approach the credit risk function is not a checkpoint standing in the way of sales, but a strategic management function that paves the road on which sales can move forward safely. Because every limit granted in a credit sale is also the allocation of part of the company’s capital to the customer.
03Systems, Organisation and Team Development
Throughout his career he has not only managed existing credit risk structures; he has also taken on founding leadership in organising credit risk functions, establishing and developing departments, designing role and authority architecture, and developing the professional teams that run these structures.
In Alptekin’s view of system building, organisation and people are inseparable. For many years he personally led the building of specialised credit risk teams, supporting their training and professional growth, developing their decision-making skills and empowering them with increasing responsibility.
The aim has been not just to build strong teams, but to develop organisations that make the right decisions, take initiative when needed and sustain a shared risk-management culture at every level.
04The Trade Receivables Life Cycle
Customer and dealer assessment → financial analysis → credit decision → credit limit → collateral → early warning → collection → problem receivables management He has led the building of systems in which this chain works not as disconnected activities, but as interconnected parts of a single trade receivables life cycle.
Alongside credit policies, decision and authority mechanisms, limit systems, risk-monitoring models, early-warning structures and collection processes, he has also pioneered new and alternative collateral models that respond to changing commercial needs.
“Strong management is not only about making the right decisions; it is about building the system and organisation in which the right decisions can be produced independently of individuals.”
05Continuous Renewal and the Learning Organisation
In Alptekin’s view, long experience does not mean repeating what was learned in the past. As economic conditions, technologies, data sources, customer behaviour, financing models and risk tools change, he argues that leaders, teams and management systems must be able to change too.
This view treats building not just working systems, but organisations that can learn, question themselves and grow by adapting to change, as part of system leadership.
“When the music changes, so must the dance.”
06Bringing Financial Risk Data to the Real Economy
In work carried out with his organisation, he moderated and led initiatives to bring Credit Bureau (KKB) and Findeks risk information into the real economy’s commercial credit assessment processes and to develop its use.
This work helped traditional financial analysis evolve into a more holistic credit assessment approach, supported by the customer’s current payment behaviour and risk indicators.
07Professional and Industry Leadership
For many years he served as Vice President responsible for the private sector and as a Board Member of the Association of Bank and Market Intelligence Professionals.
He also chaired the Private Sector Credit Intelligence Professionals’ Union for many years, leading efforts to develop a culture of credit intelligence and credit risk management in the real economy, to share professional knowledge and to institutionalise the field.
08Leadership in Times of Crisis
Alptekin has led credit risk management for large commercial ecosystems through periods when customers’ and dealers’ cash flows were severely affected, such as economic crises, sector downturns, the COVID-19 pandemic and major earthquakes.
In these periods, rather than simply tightening credit or accelerating collection, he focused on managing the balance between the customer’s business continuity, the sustainability of sales, the protection of receivables and the company’s risk-bearing capacity.
“The true success of risk management is not just managing problem receivables; it is building in advance the system that keeps a problem from becoming a crisis.”
IVROLE AT ALMERA
Turning Experience into an Institutional System
The real value lies in turning experience into institutional memory, decision models, capable organisations, measurable processes and sustainable systems. This is where the idea behind ALMERA was born.
Mehmet Nuri Alptekin founded ALMERA Credit Sales and Receivables Management Systems to make his many years of credit risk and trade receivables experience available no longer within a single corporate structure, but to companies in different sectors that sell on credit.
The aim is not to copy methods that worked in the past onto other companies. Taking into account each organisation’s sales model, customer base, capital, cash flow, risk-bearing capacity and culture, the aim is to build a trade receivables management system specific to that organisation .
ALMERA projects are carried out under Mehmet Nuri Alptekin’s management, methodology and system-building leadership, together with financial analysts, finance professionals, technology specialists and experienced partners and advisers, depending on the project.
ALMERA’s aim is not to stop companies from taking risk, but to build systems that allow healthy, visible risks to be taken, open the way for credit sales, turn receivables safely into cash, protect the company’s capital and strengthen working capital and cash flow.

