




WHY ALMERA?
The financial cycle that begins with a sale is completed with cash.
A credit sale is not merely a commercial decision. It is the allocation of part of the company’s capital to the customer.
That is why customer assessment, credit limits, collateral, early warning, collection and problem receivables management cannot be treated as separate processes. ALMERA brings these areas together under a single trade receivables management architecture.
-
 CUSTOMER ASSESSMENTKnowing the right partner through the right data.
-
 CREDIT LIMITAllocating risk in proportion to capital.
-
 COLLATERAL MANAGEMENTBuilding protection matched to risk.
-
 RISK MONITORINGSpotting deterioration through early signals.
-
 COLLECTIONTurning sales into cash in the bank.
-
 RECOVERY AND LEARNINGFeeding lessons from problem receivables back into the system.
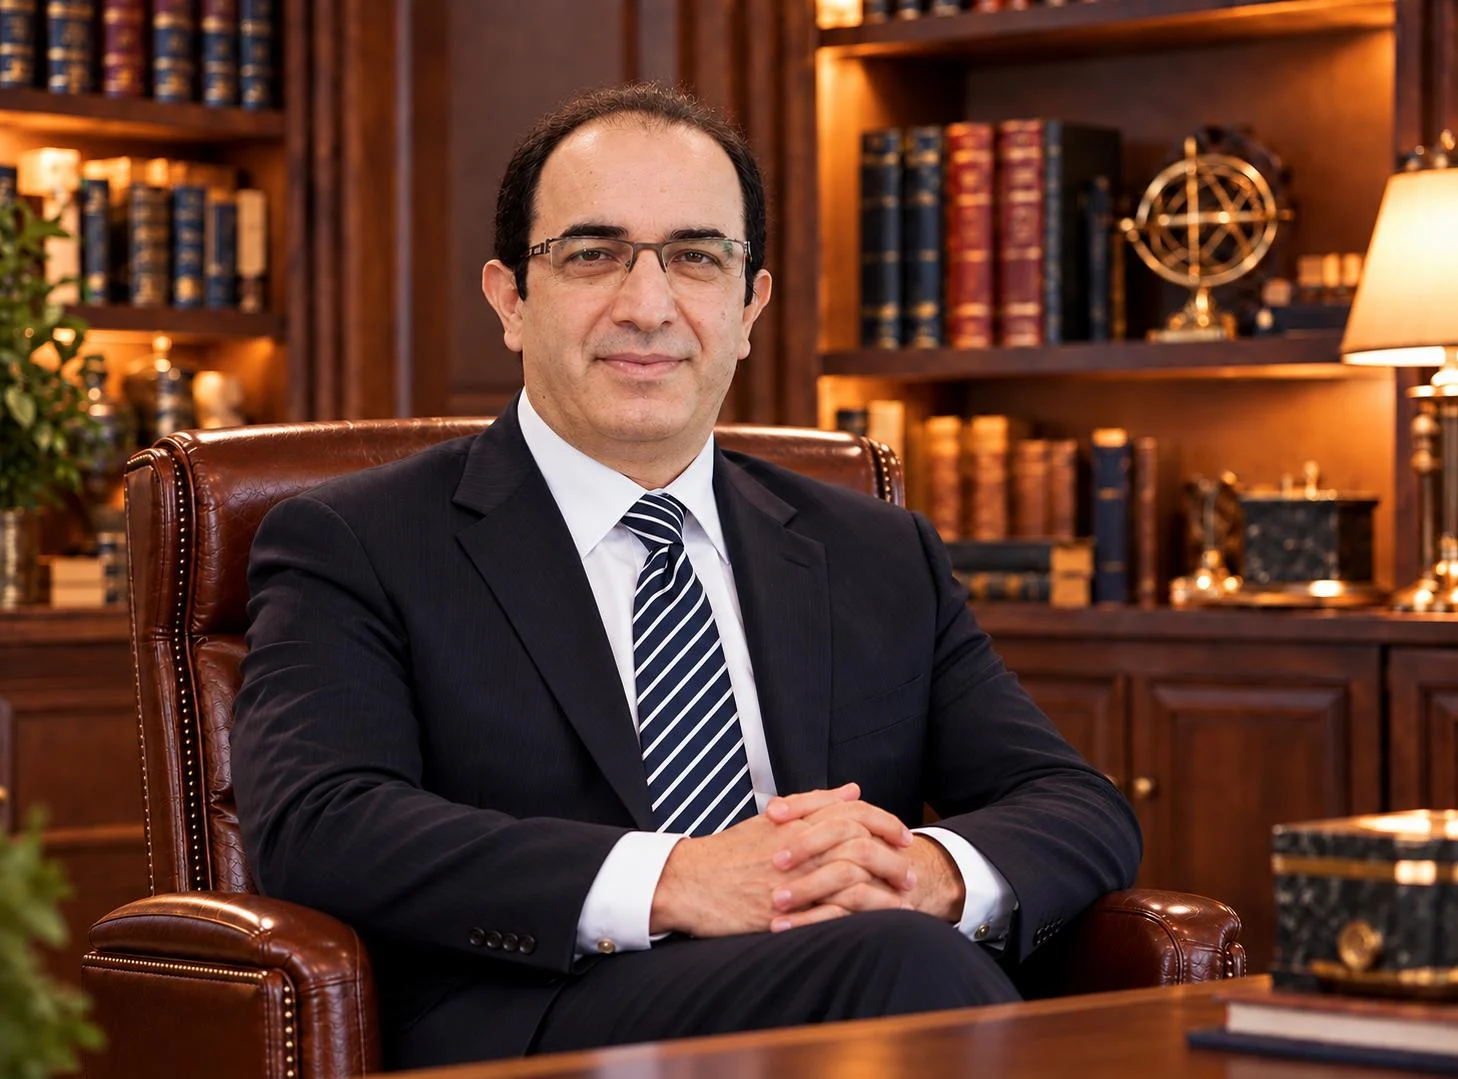
FOUNDER
Mehmet Nuri Alptekin
Founding Partner
He has spent much of a professional career spanning more than forty years in commercial credit risk, receivables, collateral and collection management. The field and senior management experience he gained across large-scale customer and dealer networks forms the foundation of ALMERA’s approach.
ALMERA was born from the idea that this experience should not remain knowledge tied to individuals, but be turned into measurable, workable management systems that organisations can sustain within their own structures.
“A well-managed trade receivables structure does not limit a company’s growth; it strengthens it.”


OUR PRINCIPLES
Tailored. Independent. Confidential.
-

Independence
Our recommendations are independent of any motive to sell commercial products or financing.
-
Tailored to You
Every company’s customer base, capital and risk-bearing capacity is different; the system is built accordingly.
-

Practicability
The value of a recommendation lies not only in being right, but in being workable within the organisation.
-

Confidentiality
Company and customer information is handled in line with confidentiality and data security principles.